Businesses at any stage in their life cycle can benefit heavily from creating and implementing a business plan.
Not only is a business plan there to map out your goals and aspirations, but also to identify any financial risks and operational challenges you may encounter.
According to research conducted by Fundsquire, 20% of small businesses fail in the first year, and around 60% fail within the first three years of trading, while CB Insights discovered:
• 29% fail because they ran out of cash
• 18% fail because of pricing and cost issues
• 17% fail due to a lack of a business model
• 14% fail because of poor marketing.
A business plan will usually outline strategies to avoid all of these issues – that’s why it’s important to create a thorough plan as early as possible in your business journey.
Here are some things you should include and what your business plan can do for you.
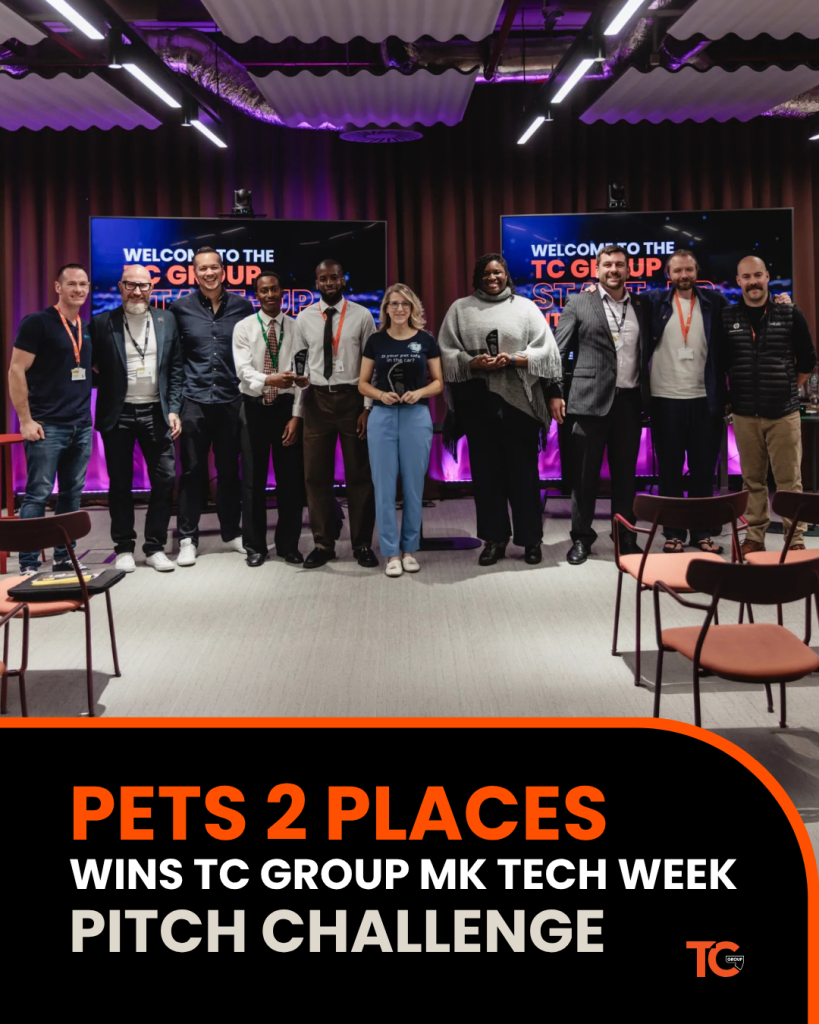
PETS 2 PLACES CROWNED WINNER OF TC GROUP’S START-UP PITCH CHALLENGE AT MK TECH WEEK
Pets 2 Places, founded by Claire Harris, has been crowned the overall winner of TC Group’s Next Big Thing: Start-Up Pitch Challenge, following a live final showcasing ambitious founders and innovators as part of Milton Keynes Tech Week 2026. Eight... Read more
TC GROUP MARKS STRATEGIC EXPANSION INTO NORTHERN IRELAND WITH GMCG MERGER
TC Group is delighted to announce its expansion into Northern Ireland through a merger with the highly respected accountancy firm GMcG. GMcG will continue to serve clients from its offices in Belfast, Lisburn and Portadown, maintaining its strong local presence... Read more
Inheritance tax planning is about more than reducing a future tax bill. The right strategy can help protect your wealth, prevent valuable assets from being sold to meet an IHT liability and ensure your family has the funds and information they need to guarantee peace of mind.