Simply put, Corporation Tax is the tax paid if your business is making a profit.
HOW MUCH DO I HAVE TO PAY?
From 1 April 2023 the Corporation Tax rate changed, meaning that a standalone company making profits of £250,000 or above are required to pay the new tax rate of 25%
Small businesses and other companies with profits below £50,000 will remain at the old tax rate of 19%.
If you’re making a profit between £50,000 and £250,000 for the tax year, you may be able to claim Marginal Relief. Marginal Relief provides a gradual increase in Corporation Tax, meaning the tax due is calculated at 25% but is reduced down using a Marginal Relief calculation.
WHEN DO I HAVE TO PAY?
Corporation Tax is normally due after 9 months and 1 day after the company’s accounting year ends.
For example; if your year-end is the 31 December, you’ll pay the Corporation Tax by the 1 October the next year.
PAYMENTS ON ACCOUNT
For large companies making between £1.5 million to £20 million in profit per year, Corporation Tax will be paid electronically via instalments.
For accounting periods of 12 months, you’ll need in pay in four quarterly instalments:
The first payment will be six months and 13 days after the 1st day of the accounting period
The second payment will be three months after the first payment
The third payment is paid another three months after the second payment (14 days after the year-end)
The fourth and final payment is three months and 14 days after the year-end
However, there are some exceptions:
If the total tax liability for the 12 months is less that £10,000.
If the profits for the accounting period are less than £10 million and either:
The company didn’t exist last year.
The company was not considered ‘large’. There’s a 1-year grace period on instalment payments after the benchmark of being a ‘large’ company is reached.
HOW ARE MY INSTALMENTS CALCULATED?
Instalments are calculated by estimating your Corporation Tax liability for the accounting period, and dividing that number by four.
VERY LARGE COMPANIES
For very large companies earning more than £20 million annually, tax is also paid in quarterly instalments which’ll look similar to:
First payment – two months and 13 days after the accounting period
Second payment – three months after the first instalment
Third payment – three months after the second instalment
Fourth payment – three months after the third instalment
Exceptions:
Similar to larger companies, if your annual tax liability is less than £10,000 it’s not necessary to pay in instalments.
However, whereas large companies have a one-year grace period after reaching the large company threshold, the very large companies don’t have the same grace period. A business is considered very large as soon as the £20 million profit mark is reached.
WHAT HAPPENS IF I PAY LATE?
Late quarterly payments will result in interest needing to be paid on top of your quarterly instalments.
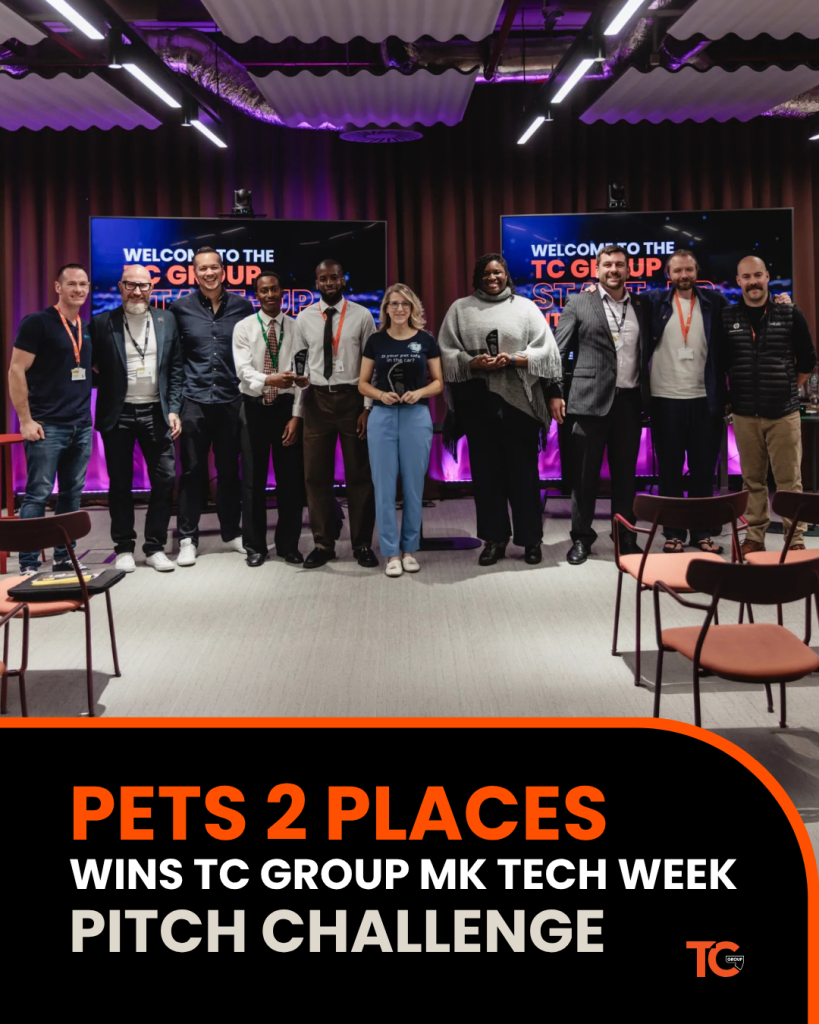
PETS 2 PLACES CROWNED WINNER OF TC GROUP’S START-UP PITCH CHALLENGE AT MK TECH WEEK
Pets 2 Places, founded by Claire Harris, has been crowned the overall winner of TC Group’s Next Big Thing: Start-Up Pitch Challenge, following a live final showcasing ambitious founders and innovators as part of Milton Keynes Tech Week 2026. Eight... Read more
TC GROUP MARKS STRATEGIC EXPANSION INTO NORTHERN IRELAND WITH GMCG MERGER
TC Group is delighted to announce its expansion into Northern Ireland through a merger with the highly respected accountancy firm GMcG. GMcG will continue to serve clients from its offices in Belfast, Lisburn and Portadown, maintaining its strong local presence... Read more
Inheritance tax planning is about more than reducing a future tax bill. The right strategy can help protect your wealth, prevent valuable assets from being sold to meet an IHT liability and ensure your family has the funds and information they need to guarantee peace of mind.